We deliver local knowledge backed by global strength.
With presence across the continents, we enable our member firms to deliver services that are locally relevant and globally aligned with international standards.

Our Network
Our Network

Insights
Insights
Business Insights providing executives with straightforward and strategic perspectives on key challenges: reshaping business models, addressing climate change and sustainability, and cultivating trust amidst rapid technological advancements.
All Insights
Services
Services
Our collaborative and transparent service portfolio includes assurance, business advisory, tax compliance and planning, risk assessment, and technology services. We prioritize integrity, objectivity, and confidentiality. With personalized strategies, we excel in meeting diverse client needs through a client-centric and proactive approach.
All Services
Industries
Industries
At PA Global, we stand as your reliable partner in navigating today’s complex and evolving business landscape. Our team of seasoned professionals brings deep industry expertise and a commitment to delivering tailored, forward-thinking solutions that empower organizations to grow sustainably and operate with resilience.
All Industries


 PA Academy
 Members Portal
Live webinar
Introduction to IFRS 18
Presentation and Disclosure in Financial Statements
Thursday 26 November 2026 · 1:00 – 3:00 PM Dubai time (GST, UTC+4)
Register nowDate
Thursday 26 November 2026
Time
1:00 – 3:00 PM Dubai time (GST, UTC+4)
Format
Live online webinar
IFRS 18 replaces IAS 1 for annual periods beginning on or after 1 January 2027 — and because it applies retrospectively, the 2026 comparatives are already in play. Join us for a practical walkthrough of what changes, what stays the same, and how to get your financial statements, chart of accounts and systems ready.
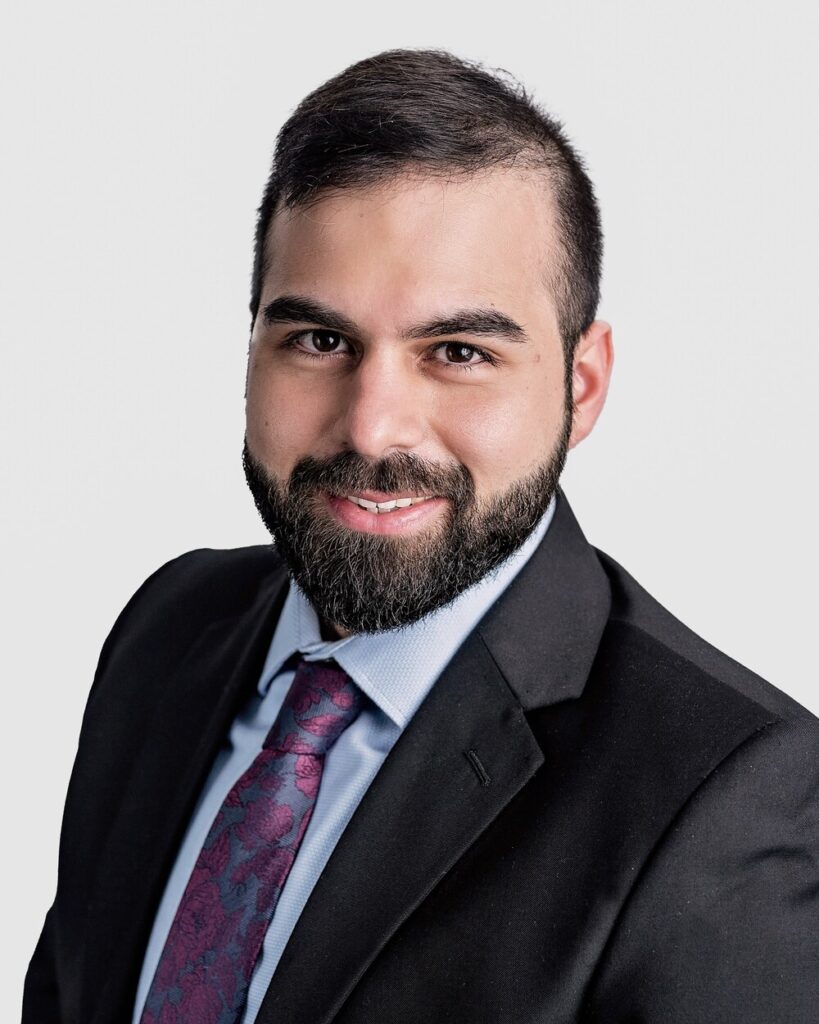
Your presenter
Mr. Wael Youssef
CPA
Wael Youssef is a Certified Public Accountant with around ten years of experience in audit and financial accounting. He leads audit engagements and performs engagement quality control reviews, working across manufacturing, retail, hospitality, healthcare, real estate and not-for-profit organisations.
During his career at Deloitte, Wael led data analytics initiatives, supporting audit teams in integrating analytics into their audit procedures to improve efficiency and promote a more structured and systematic audit approach. He worked across the firm’s offices in Lebanon, Saudi Arabia and Canada, and works in both local standards and IFRS.
Wael also has mentoring and teaching experience through his involvement in a digital mentoring programme designed to introduce mentees to the professional world, guide them in planning and pursuing their educational paths, and support their transition into the job market.
Presentation and disclosure is one of his core service areas, which is the ground IFRS 18 changes.
Programme
-
Welcome and introduction
Opening remarks and the objectives of the session
-
01 Overview
What IFRS 18 is, why it replaces IAS 1, its scope, the objective of financial statements, materiality and the effective-date timeline
-
02 Structure of the Financial Statements
The complete set of statements, the five income statement categories, main business activity tests, the two new subtotals, expense analysis and each primary statement, closing with group application: entity and consolidated classification, intragroup eliminations and group mappings
-
03 MPMs & Aggregation / Disaggregation
Management-defined performance measures, the definition tests, required disclosures, a worked reconciliation and the sharper aggregation rules
-
04 Other Presentation & Disclosure Changes
Notes structure, entity-level and capital management disclosures, requirements relocated to IAS 8, consequential amendments and a full IAS 1 vs IFRS 18 recap
-
05 Impact Assessment & Readiness
Transition, industry-specific impact, the implementation roadmap, chart-of-accounts rebuild, timeline and what we need from you
-
06 Open discussion, Q&A & next steps
Readiness checklist, questions from participants and proposed next steps
-
Close
Key takeaways
- What changes from IAS 1, and what does not
- Classifying income and expenses into the five categories
- When a measure becomes an audited MPM, and when it cannot be one
- Applying IFRS 18 across a group, at entity and consolidated level
- A practical roadmap for the 2026 comparatives
Register for this webinar
Registration takes a moment. You will receive the joining link by email once you have registered.
Register nowOpens the registration form in a new tab.